Prefer to talk to a pro?
Call today, and let us connect you with the perfect merchant!
Call today, and let us connect you with the perfect merchant!
About White House, TN
White House is a part of the Robertson and Sumner counties region in area of Tennessee known for its trail running from Kentucky to Nashville, originally created by buffalo and Native Americans and fastest prospering economies in Tennessee. Major attractions include White House Inn Library and Museum. The choir at the Church of White House recorded back-up vocals for the adventure film ."O Brother, Where Art Thou?".The biggest schools here are White House Middle School and White House High School. One of the best places to visit when you are in White House is First Baptist Church of White House. Famous persons from White House include John Decker the town's current mayor and Alison Krauss an American bluegrass-country singer, songwriter.
Best Businesses in White House, TN


Prefer to talk to a pro?
Call today, and let us connect you with the perfect merchant!
Call today, and let us connect you with the perfect merchant!
Related articles
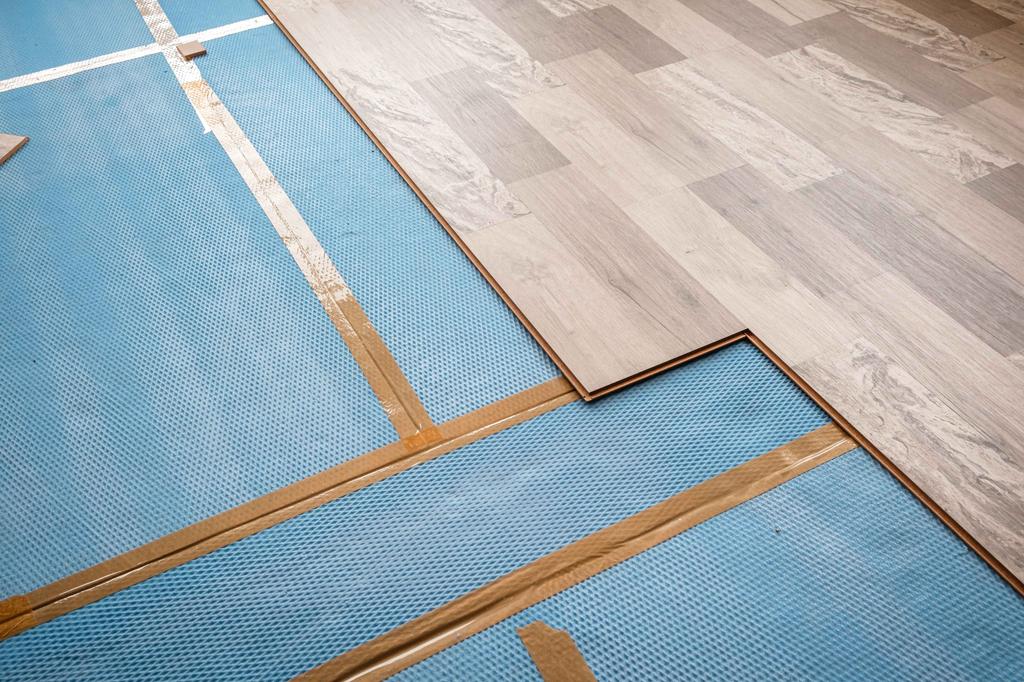
How to Fix Squeaky Floors: Easy DIY Solutions That Actually Work
Landscaping Gravel Types: Pros and Cons
How to Clean Hardwood Floors: Simple Steps for Long-Lasting Shine
Updates & tips
It is crucial to choose a mortgage broker
When you are looking for a mortgage, the rates are the most important. Rates can vary widely. To get accurate rates, you need to know as much information as possible. The amount you pay will be affected by your credit score, income, and loan-to-value. You can find rates in the newspaper, online, and on the radio. What should you look out for in a mortgage broker 1. Be Suspicious Many loans are available at different rates. There are many loans available with different rates. It can be hard to figure out the rate that you will pay. Are you satisfied with the rate that you are paying? Would you like to know the rate you are paying? You will get the bestmortgage lender in Nashvillewith the lowest rates. If a broker offers rates immediately, don't be surprised. This is often a salesperson trying to convince you to buy more. 2. You must be prepared A good mortgage broker will take time to get to know you and ask questions. Prepare. It is vital to monitor your credit scores. You can check your credit score on many websites. You can go through each one. An additional charge is required to obtain a uni-merged credit report which includes your credit score. This is a great way to obtain a tri-merged credit report before you apply for a loan. Calculate your monthly gross earnings. If you're married, calculate your gross monthly income. This is your income that is not subject to tax. Find out the ratio of your rear and front ends. The front-end ratio is the amount of income you have that goes toward housing expenses. Renters pay the rent amount. Your principal taxes, insurance sums, interest, and insurance premiums are paid by homeowners. This number may also include the mortgage premium which is often paid by top mortgage lenders and homeowner association dues. The back-end ratio is the income that was used to pay all recurring loans. This includes all the debts that are not included in the front-end ratio. You will see the amount of debts on your credit report. Your front-end ratio should not exceed 28 percent and your backend should not exceed 36% of your monthly income. 3. Be Honest Honesty is a two-way road. Do not exaggerate your earnings or credit score, as it will eventually catch up with you. Your information could impact the rates you are offered. You must communicate with your broker. Only honest and open conversations can help you choose the right mortgage option for your needs. It's not a good idea for you to offer low rates in order to help you sell. 4. Don't fall for the trap! Do not fall for the switch and lure marketing tactics you are constantly being bombarded with. It's everywhere. Every day, we see the same mortgage advertisements on our way to work. It is unlikely that it will succeed, but his methods are not doubtful. We prefer to follow the flow. We believe that success is dependent on my ability see the whole picture and understand how it affects you business. These tips will make your next mortgage as profitable and easy as possible. We want you to understand the process, not just get the lowest rate or the lowest price. This is the only way to protect yourself from sharks in water.
What Are The Signs Of Mortgage Loan Fraud?
Each day, we hear about another fraudulent mortgage company closing down. Banks have raised their criteria for people who can get mortgages due to tightening market conditions. This has a significant impact on mortgage brokers and companies that have helped people obtainmortgage loans in Nashvillefrom traditional banks. These days are gone. These days, smaller mortgage brokers and firms must now offer the exact same products as large banks. The majority of consumers are not able to get the same benefits from a broker as they would if they used a bank. Smaller brokers and mortgage companies offer a more personal experience than larger banks. Smaller brokers can help you get a loan approved and will recommend the right banks to place your mortgage. For the "plain Jane" consumer with good credit and equity, however, it's not necessary to have them use an agent. This market segment made up a large part of smaller mortgage companies' business. The economy tends to eliminate the rats when it is tightened. That's why we wrote this article. 1. Complete or blank paperwork Although it may sound obvious, it is amazing how many times it happens. The borrower must receive two types of documentation from the mortgage company before they approve the loan. The first set of documentation is an estimate that the loan officer (LO), has compiled. After you have signed the documents, the second set of documentation is the exact numbers you will need to submit. After gaining their trust, false LOs will request that customers complete a blank disclosure form. They will make excuses such as "the numbers are likely to change regardless, so don’t stress about how many pages” or "we won’t know the true numbers until we get an appraisal." They will often give you a verbal rate, or a payment estimate, and then ask you to sign the RESPA disclosures. If you are asked, do not sign any blank documents. Closer numbers will be much higher than you expected. You will need to decide whether to cancel an unfavorable loan or start the process of getting a mortgage. You may be required to sign a disclosure that is incomplete. However, you should not sign anything until all disclosures have been completed. Completed disclosures enable the user to review what they were asked to sign and to compare it with actual numbers. The LO can clearly explain discrepancies to the user and not dismiss them as trivial. 2. They insist on using their attorney or title company to close the loan Although it is possible you may not have noticed, closing lawyers often follow mortgage guys in news reports. Disclosures are essential documents that borrowers must sign before they can apply for a mortgage. The disclosure states that the borrower can choose their closing agent. Many mortgage companies, honest or not, assume you will use your closing agent. Most mortgage lenders have a process in place that allows them to close loans quickly. Some lenders are more efficient and competitive than others, while others do not. To determine if your title company and your mortgage company are compatible, ask your LO to send you a copy of the closing company rate sheet. This will allow you to compare rates. Do not let your LO pressure you into using their closing agent or insist that you use their company. Good LOs and mortgage firms will respect your right to choose the closing agent that suits you best. They will also know that if they do not respect your request, they may be in violation of RESPA laws and lose their license. 3. The Department of Finance and Banking Information doesn't match Each state has its own bank and finance department that regulates mortgage companies. A mortgage firm must provide their contact information, as well as the physical address and name of the person or entity holding the license, in order to obtain a license. This information is usually available online and available to the general public. To verify the address on your license and the address provided by the mortgage company, visit the official government website. This could indicate a potential warning sign. Before making any decisions, it is a good idea to contact the department for banking and finance if the name of the license holder is different from the company that was told to you.
Buy Positive Reviews Online
Buy Positive Reviews Online Having a relevant, current, and positive online reputation has a direct impact on bottom-line sales. The team at Blue Ocean Global Technology (link is external) is proven to help clients, large and small, to develop and protect technology assets to maintain organizational health and improve performance. Only one key aspect of online reputation management is to implement a strategy for getting positive online reviews. What others have to say about your company is critical to your success. Knowing that potential customers will research your business and products before interacting with your sales team should cause you to wonder what they will think after viewing search engine results pages (SERPs). What does your online reputation say about you? When was the last time you checked to see if the information was correct? If you are not certain of your answers to those two questions, you may have already lost business without knowing why. Don̢۪t wait until someone else points out a negative review. Work actively and diligently to develop and maintain a positive online reputation. By doing so, you will maximize the impact of positive press, build trust and customer confidence, enhance your public image, improve customer retention, and attract top talent while increasing sales revenue. Online reputation management is one of the single best things you can do for the success of your business, beyond providing an excellent product and exceptional service.